
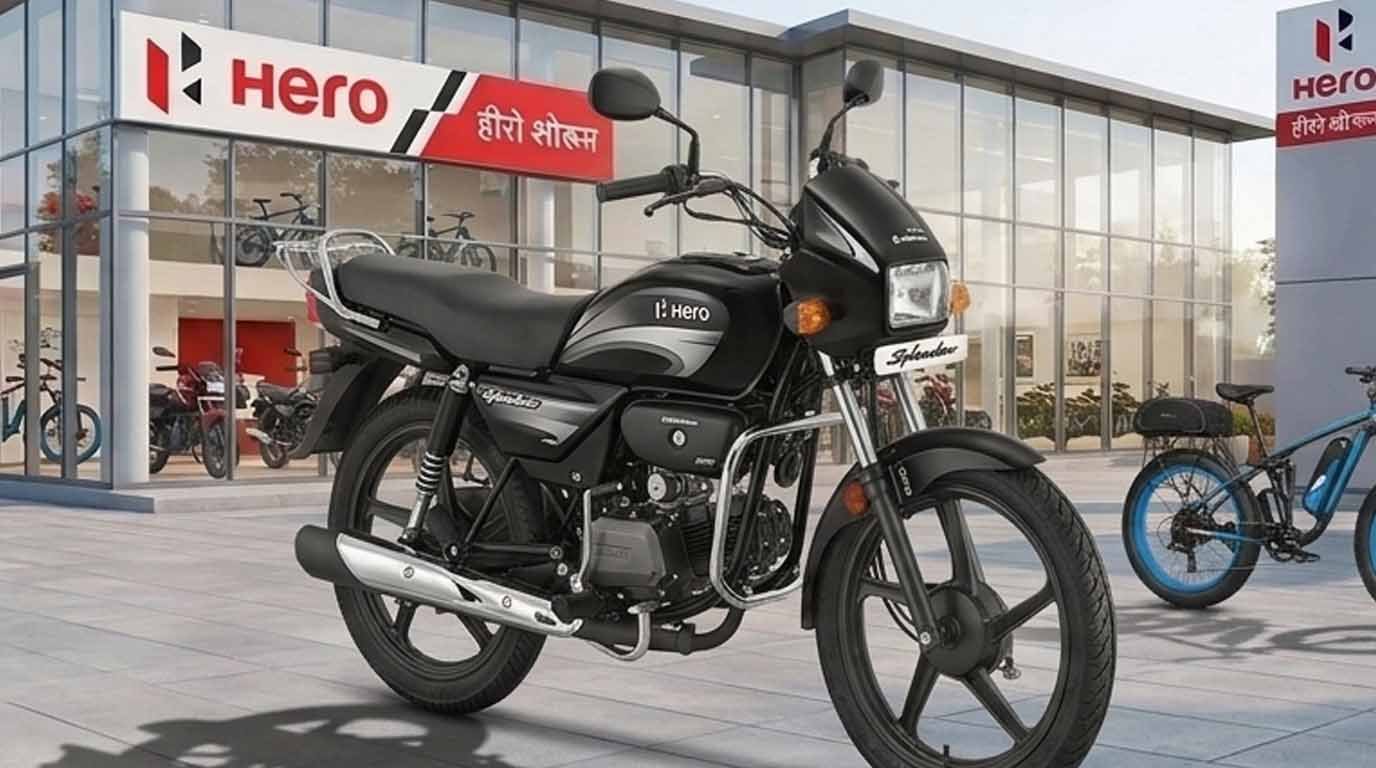
The Hero Splendor is a popular commuter motorcycle in India, known for its practical design, fuel efficiency, and everyday usability. Many people consider purchasing this motorcycle through a two-wheeler loan because paying the entire amount upfront may not be convenient. Bike finance offers can help eligible buyers purchase a motorcycle by paying an initial down payment and repaying the remaining loan amount through monthly instalments.
Before choosing a finance plan, buyers should understand the available loan options, interest rates, eligibility criteria, required documents, and repayment process. This guide explains how Hero Splendor bike financing generally works and what customers should check before applying.
Please note that finance offers, interest rates, and eligibility requirements vary between lenders, dealerships, and applicants. The details below are general guidance, not a guaranteed loan offer or confirmation of any government subsidy.
Understanding Hero Splendor Bike Finance Offers
Two-wheeler finance allows a customer to purchase a motorcycle with financial assistance from a bank, non-banking financial company (NBFC), or another authorised lender. Instead of paying the complete on-road price immediately, the buyer pays a portion of the cost as a down payment. The lender finances the remaining eligible amount.
For example, if a motorcycle’s on-road price is ₹90,000 and the buyer pays ₹20,000 upfront, the remaining ₹70,000 may be financed, subject to lender approval and applicable charges.
The actual price of a Hero Splendor depends on the model, variant, location, insurance, registration charges, and other applicable costs. Buyers should obtain a current quotation from an authorised Hero MotoCorp dealership before comparing finance offers.
Hero Splendor Bike Loan Interest Rates
Interest rates are one of the most important factors when selecting a motorcycle loan. Lenders may offer different rates depending on the applicant’s income, credit history, repayment capacity, loan amount, tenure, and internal lending policies.
Some lenders advertise special interest rates during promotional periods. However, an advertised rate may not apply to every applicant, and some offers may include processing fees or other conditions.
Before accepting a loan, ask the lender to explain:
- The annual interest rate and whether it is fixed or variable.
- The total amount being financed.
- The monthly EMI and repayment period.
- Processing fees and other applicable charges.
- Late-payment penalties and foreclosure conditions.
- The total amount payable over the complete loan tenure.
Comparing the total repayment cost is more useful than choosing a loan based only on a low advertised interest rate.
Down Payment and Loan Amount
The down payment is the amount a buyer pays from personal funds when purchasing a motorcycle. The remaining eligible amount may be covered by the loan.
The required down payment varies according to the lender’s policy, the motorcycle’s price, the applicant’s eligibility, and the finance offer. Some lenders may provide a higher loan-to-value ratio to eligible customers, while others may require a larger upfront contribution.
A larger down payment generally reduces the amount borrowed. This can lower the EMI and the interest paid over the loan period, depending on the loan terms.
However, buyers should not use all their available savings for a down payment. It is sensible to keep sufficient money for insurance renewals, fuel, servicing, registration-related expenses, and emergencies.
Hero Splendor Bike EMI Options
Equated Monthly Instalments, commonly known as EMIs, are regular payments made to repay a loan. Each payment generally includes a portion of the principal and the applicable interest.
The EMI depends on the loan amount, interest rate, and repayment tenure. A longer tenure may reduce the monthly payment but can increase the total interest cost. A shorter tenure may result in a higher EMI while reducing the overall interest expense.
For illustration, consider a loan of ₹70,000 at an assumed annual interest rate of 12%, calculated using a standard monthly reducing-balance method.
| Loan tenure | Approximate monthly EMI |
|---|---|
| 12 months | ₹6,220 |
| 24 months | ₹3,295 |
| 36 months | ₹2,326 |
These figures are illustrative estimates only. They exclude processing fees, insurance financing, and other charges. The actual EMI may differ according to the lender’s calculation method and final loan agreement.
Before selecting a tenure, check whether the monthly instalment fits comfortably within your regular budget.
Eligibility Criteria for a Two-Wheeler Loan
Eligibility conditions differ among lenders, but applicants are commonly assessed using the following factors.
Age: The lender may specify minimum and maximum age limits for borrowers.
Income: Applicants may need to demonstrate a regular source of income or sufficient repayment capacity. Salaried employees and self-employed applicants may have different documentation requirements.
Employment or business stability: Some lenders consider the length of employment or the stability of a business when evaluating an application.
Credit history: A credit report and repayment history may influence loan approval, interest rates, and the amount offered.
Identity and address verification: Applicants generally need valid documents to establish their identity and residential address.
Meeting the basic criteria does not guarantee approval. The lender makes the final decision after reviewing the application and supporting information.
Documents Required for Hero Splendor Bike Finance
Applicants should confirm the exact document list with their chosen bank, NBFC, or dealership finance representative. Commonly requested documents include:
- Aadhaar card or another accepted identity document.
- PAN card, where required by the lender.
- Proof of residential address.
- Recent salary slips or other income evidence, if requested.
- Bank statements for the period specified by the lender.
- Passport-sized photographs, if required.
- Completed loan application form.
- Motorcycle quotation or pro forma invoice from the dealership.
Self-employed applicants may need additional business or income documents. Keep copies of documents secure and submit them only through verified lender or dealership channels.
Step-by-Step Hero Splendor Bike Loan Process
Step 1: Select Your Motorcycle
Choose the Hero Splendor variant that meets your needs and budget. Confirm its ex-showroom price, on-road price, available colours, and delivery availability with an authorised dealership.
Step 2: Compare Finance Offers
Check finance options available through banks, NBFCs, and authorised dealership partners. Compare interest rates, processing fees, down payment requirements, repayment tenure, and total repayment cost.
Step 3: Calculate Your Budget
Estimate how much you can pay upfront and what monthly EMI you can comfortably manage. Remember to account for fuel, insurance, servicing, and regular household expenses.
Step 4: Submit the Application
Complete the application through the lender’s official website, verified application portal, or authorised dealership. Enter accurate details and upload the requested documents.
Step 5: Complete Verification
The lender may verify your identity, address, income, employment, and credit history. It may also request additional information before making a decision.
Step 6: Review the Loan Agreement
If the application is approved, read the sanction letter and loan agreement carefully. Check the interest rate, EMI, tenure, fees, payment dates, and applicable penalties before accepting the terms.
Step 7: Complete Payment and Delivery
Pay the agreed down payment and complete the dealership’s purchase formalities. Vehicle registration, insurance, and delivery arrangements should be confirmed with the dealer before taking possession of the motorcycle.
Tips for Choosing the Right Finance Offer
Selecting the right loan requires more than comparing the monthly EMI. A low EMI may result from a longer repayment period, which could increase the total interest payable.
Request written quotations from multiple lenders and compare the annual interest rate, processing charges, and total repayment amount. Ask whether any advertised discount is conditional on using a particular lender or purchasing additional products.
Avoid signing blank forms or accepting unclear charges. Do not share OTPs, banking passwords, or PINs with anyone claiming to arrange a bike loan. Apply through official channels and keep copies of all agreements and payment receipts.
If a dealer advertises zero-down-payment finance or a special interest rate, confirm the complete conditions in writing. Such offers may have eligibility requirements and may not be available in every location.
Common Mistakes to Avoid
Some buyers focus only on the down payment and overlook the total cost of financing. Others choose a longer tenure without checking the cumulative interest, or accept an offer without understanding the processing fees.
Another common mistake is assuming that a loan is approved simply because an online form has been submitted. Final approval depends on the lender’s verification process.
Buyers should also avoid unofficial agents who promise guaranteed approval in exchange for advance payments. Verify the lender’s identity and never rely on unconfirmed claims about government-sponsored free bikes or guaranteed subsidies.
Benefits of Financing a Hero Splendor
Financing may allow eligible buyers to purchase a motorcycle without paying its full price upfront. Monthly instalments can make the purchase easier to plan, while a suitable repayment schedule can help buyers manage their finances.
The benefits depend on the loan terms and the buyer’s financial circumstances. Borrowing also creates a repayment obligation, so it is important to select an affordable motorcycle and avoid taking a loan that places unnecessary pressure on the household budget.
Conclusion
Hero Splendor bike finance offers can provide a practical way to purchase a motorcycle through a down payment and monthly EMIs. Before applying, compare lenders, understand the interest rate, calculate the total repayment cost, and confirm the required documents.
The best finance option is not necessarily the one with the lowest advertised EMI. It is the option with transparent charges, manageable repayments, and terms that suit your financial situation. For accurate pricing and current offers, contact an authorised Hero MotoCorp dealership and verify the final loan terms directly with the lender.